First-home decisions · Portfolio feature
First Salt Lake home? Start with evidence.
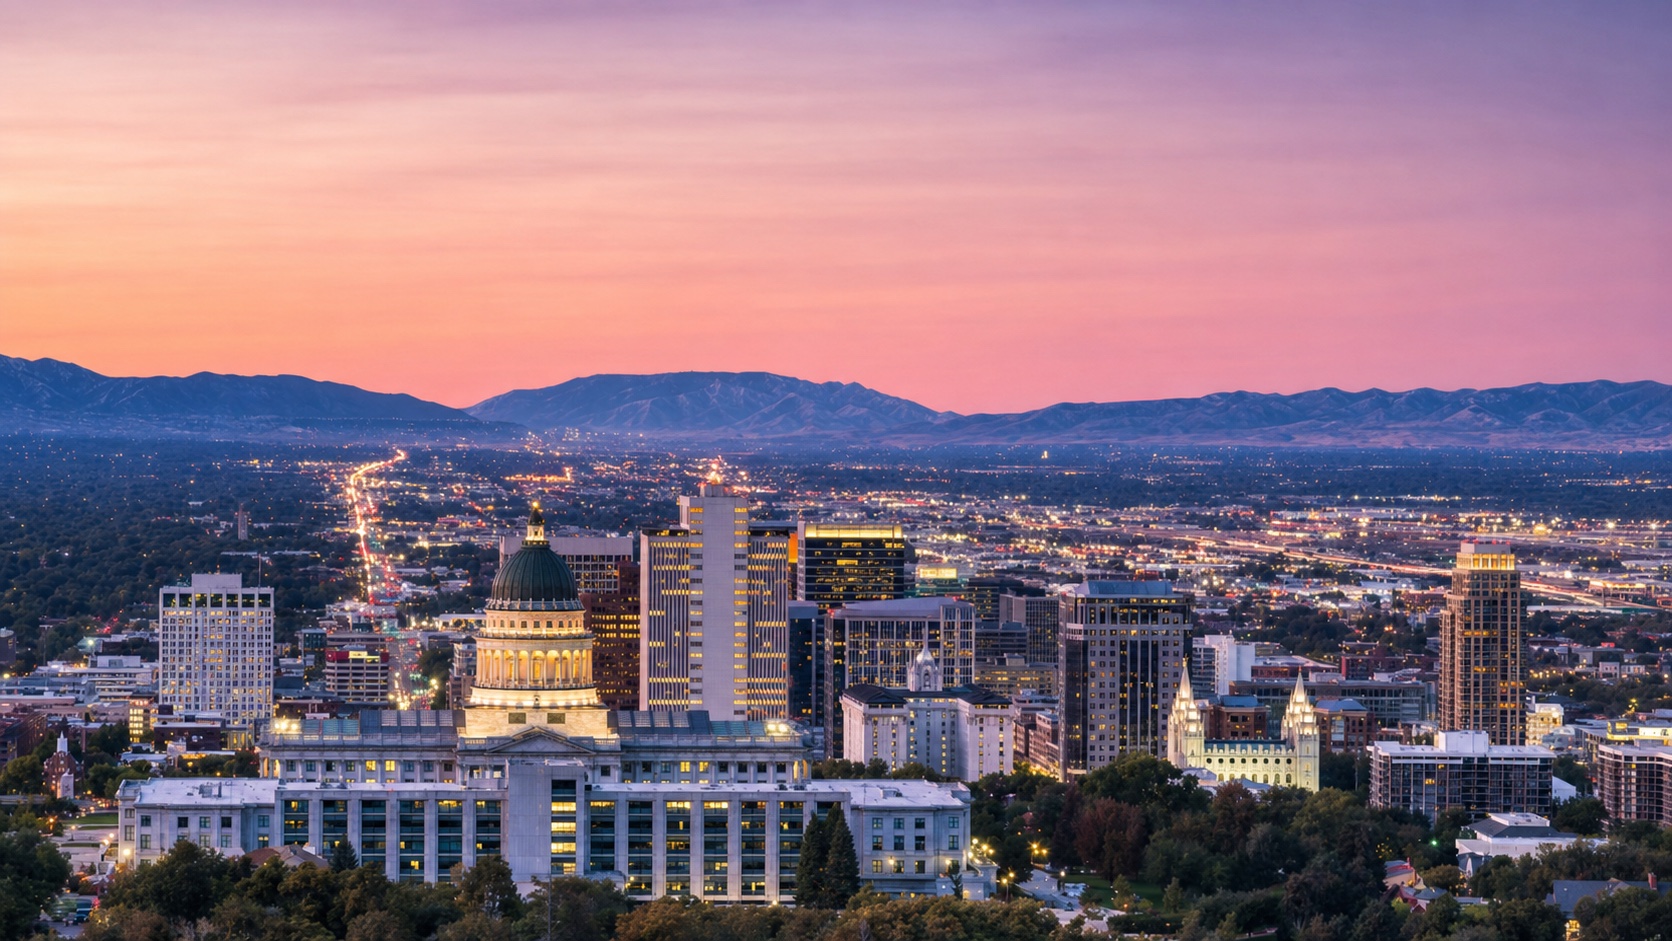
Joshua Elkington is the featured contact for first-home planning in Salt Lake City and West Valley City. The first decision is how to turn a search into a plan you can examine: a budget tied to your actual life, a lender’s written figures and a list of property questions. Each piece answers a different question. Put them side by side before the excitement of a particular home takes over.
Quick answer
How do I buy my first home in Salt Lake City?
Begin with your own monthly budget, then compare the lender’s written estimate and the property’s actual costs. Ask Joshua to help organize the home-search questions and the relevant transaction dates; confirm financing figures directly with the lender.
Keep qualification and comfort separate
A preapproval letter helps frame a search, but it does not replace a household budget. The CFPB advises buyers to revisit the total monthly payment and their priorities as they shop. Your comparison should also leave room for ordinary expenses and the costs of owning the particular home. Write down what remains comfortable when those items are included. If the lender’s number and your own limit differ, bring the difference into the conversation early. A lower personal limit can simply be a deliberate choice about the rest of your life. [1]
Ask what is behind the estimate
Use the Loan Estimate to understand the proposed payment, loan terms and cash required. Keep the date and assumptions with the document. Ask the lender what is estimated, what could change and what depends on the address you eventually choose. A comparison is easier to read when the price, down payment and loan type are consistent. Rather than turning an online calculator into an approval, use it to identify the questions that need a written answer. Update the working figures when the property or financing assumptions change. [2]
Make the property part of the evidence
A first-home shortlist should have a small evidence file for each address. Note the property information you have received, the condition questions still open and the sources you need to consult. An inspection and an appraisal serve different purposes; a lender’s valuation does not answer every condition question. Discuss the inspection scope and any specialist follow-up with the appropriate professional. Keep requests connected to the actual house. That gives the comparison more substance than asking whether a whole neighborhood is a good place to buy. [3]
Read the dates before making the promise
The Utah state-approved purchase-contract form separates several transaction milestones. The agreement you sign, including its addenda, is the document that matters for your particular purchase. Ask Joshua to walk through the proposed dates and identify which tasks depend on a lender, inspector, seller or title professional. Record who will supply the next answer and when it is needed. A contract date is more useful when it sits beside a real task. Unclear wording or a legal question should be resolved with an appropriately qualified professional before you rely on an assumption. [4]
Your evidence checklist
- A personal monthly limit with ownership expenses included
- A dated lender estimate and the assumptions behind it
- An address-specific condition and records list
- A calendar showing the next decision and who supplies the evidence
Bring Joshua your target area, comfortable budget range and the question that is stopping your first search. Ask for a clear sequence of property decisions to discuss with your lender and other transaction professionals.
Sources & further reading
Official resources checked for this guide. Compare current guidance with your actual property records, lender documents and signed agreements.
Portfolio feature: The Wasatch Post and the featured agent’s website share the Omni AI / AIS Empire network. Public sources inform the guide; the agent’s contact profile is supplied separately by the portfolio owner.